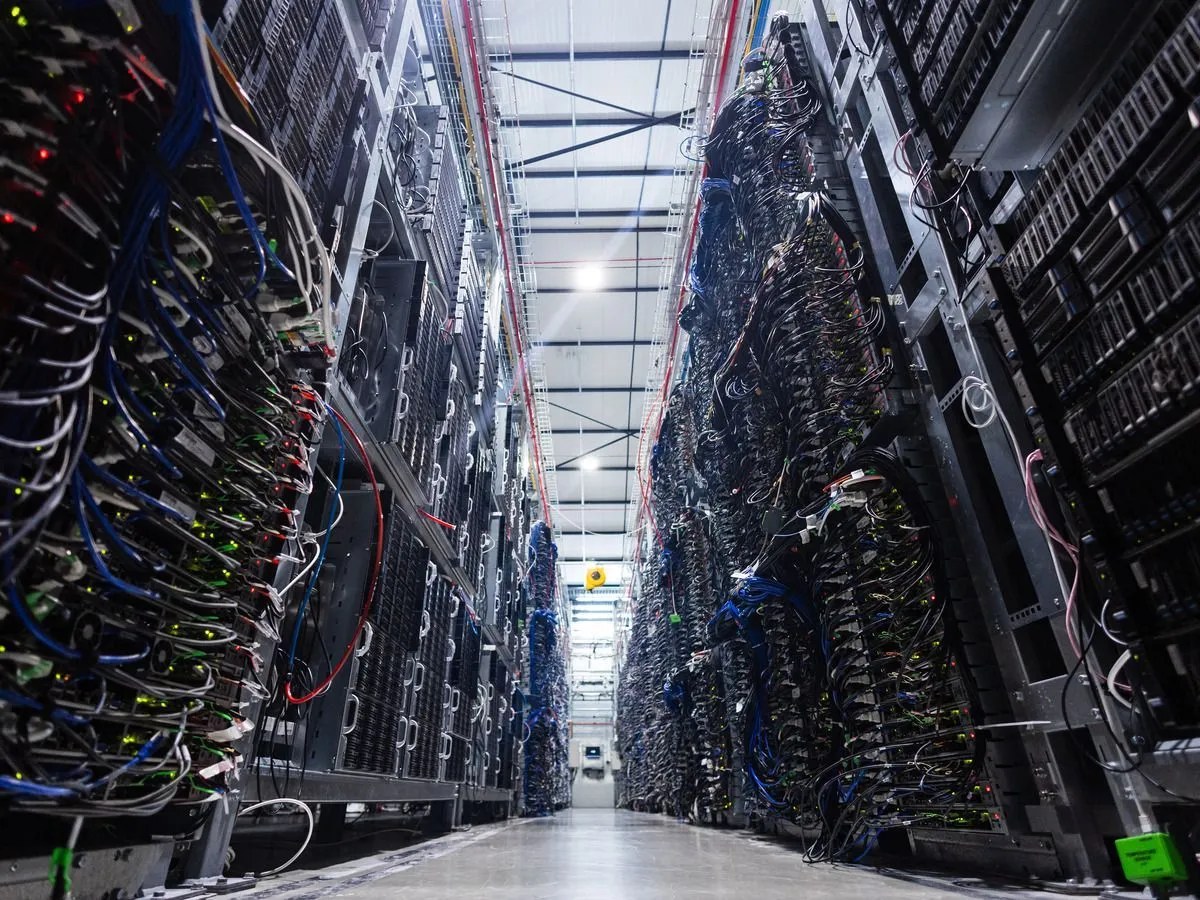
Alberta has spent the past two years collecting data centre announcements. The number that actually governs how many of them get built is smaller and far less discussed: the megawatts the Alberta Electric System Operator is prepared to connect.
Developers have asked to connect roughly 19,565 MW of data centre load. In the first stage of its large-load process, the AESO allowed 1,200 MW onto the grid. The gap between those two numbers is the single most important constraint on the province’s AI ambitions, and it is a physical constraint, not a policy preference.
The queue built quickly. By June 2025 the AESO reported 29 data centre applications for firm Demand Transmission Service representing more than 16,000 MW of cumulative requested capacity. For scale, that is a request for new industrial load on the order of Alberta’s entire existing system peak, arriving inside roughly two years and concentrated in a handful of locations.
A grid cannot absorb that. Transmission has to be planned, permitted and built; generation has to be contracted; and the costs of both land somewhere. If new transmission is socialised across the rate base, existing ratepayers subsidise hyperscalers. If it is not, projects carry costs that can make Alberta less attractive than the jurisdictions it is competing against. Every serious question about Alberta’s data centre strategy eventually reduces to that allocation problem.
The province’s answer, in force since June 2026, is the Data Centre Regulation, which directs the AESO to prioritise projects that pair their demand with dedicated new generation or storage. In practice this is a bring-your-own-generation rule: a project that shows up with its own supply moves ahead of one that expects the existing system to carry it.
That reframes what a data centre developer in Alberta actually is. It is no longer a real-estate and compute business that buys power as an input. It is a power development business that happens to run servers, and the competitive advantage sits with whoever can finance, permit and build generation on a timeline that matches a compute buildout.
The Alberta government frames the opportunity in the range of $100 billion and has said the strategy has attracted close to $200 billion in potential private investment. Those are expressions of interest, not commitments, and the connection queue is the reason to treat them carefully. Interest is abundant. Interconnection is scarce.
It is worth being precise about what has actually cleared that scarcity, because a small number of projects have. Meta has committed to a campus in Sturgeon County described at more than $13 billion, with employment figures in the range of 3,300 jobs across construction and operations. eStruxture is building an advanced facility valued at roughly $750 million carrying 90 megawatts of power. Those two projects alone account for a meaningful share of the first tranche, which tells you something about how the released capacity is distributing: not thinly across thirty applicants, but heavily toward a few very large ones.
That concentration is a predictable consequence of the rules. A hyperscaler can absorb the cost and delay of arranging dedicated generation because the compute it supports is worth enough to justify the effort. A mid-sized colocation provider often cannot. The bring-your-own-generation requirement is therefore not neutral between project types, and Alberta is, in effect, selecting for very large well-capitalised entrants. Whether that is the right outcome depends on what the province wants from the sector: tax base and construction employment, or a broad domestic compute industry with many participants. Those are different goals and the current rules favour the first.
The cost allocation question deserves more attention than it gets, because it is where the public interest sits most directly. New transmission built to serve a data centre is a long-lived asset paid for over decades. If the cost enters the general rate base, every Alberta household and business contributes to infrastructure whose primary beneficiary is a single industrial customer. If it is assigned entirely to the developer, some projects become uneconomic and go elsewhere. Most regulators land somewhere between the two, and the exact position of that line is worth more scrutiny than any announced dollar figure.
There is also a water dimension that has been slower to surface in public debate. Large facilities need cooling, and cooling in a dry province with an already allocated river system is a constraint of its own. Newer designs reduce water use substantially compared with older air-conditioned halls, but the allocation question is real in specific watersheds, and it is decided by a licensing process separate from anything the AESO controls. A project can hold a grid position and still be waiting on water.
The comparison Alberta is usually measured against is Virginia, where Loudoun County built the densest concentration of data centres in the world. That comparison is less useful than it appears. Virginia grew its cluster over roughly two decades on the back of existing fibre routes and a utility able to expand incrementally. Alberta is attempting something closer to a standing start, at a scale that would rival its entire existing system peak, inside a handful of years. The engineering problem is not the same problem, and the timelines will not rhyme.
The useful things to watch over the next year are narrower than the headline numbers: how much capacity the AESO releases in subsequent stages, how many bring-your-own-generation projects reach financial close rather than announcement, how the cost of new transmission is ultimately allocated between developers and ratepayers, and how many of the projects holding grid positions have named an anchor tenant. That last one is the quietest signal and often the most telling. A data centre without a committed buyer for its compute is a building, and buildings do not get financed on enthusiasm.
Sources
- AESO: Large Load Projects
- AESO: Data Centre Update
- Government of Alberta: AI Data Centres Strategy
- Government of Alberta: Grid
- BLG: Data centre regulation in Alberta
Figures in this article are drawn from the sources above. Spotted an error? Tell us and we will correct it.